

Instant Cash Advance

- 58.00 Reviews
- 4.6
- Downloads
- 10,000+
Our take on Instant Cash Advance from Appgk
When money gets tight between paydays, the appeal of an instant cash advance is obvious: open an app, request help, and deal with the shortfall before it turns into a missed bill. I tested Instant Cash Advance with that practical situation in mind, not as a budgeting game or a long-term financial planner. It is a finance app from Janssen Herman, aimed at people looking for fast access to borrowed funds rather than a full household money-management system.
My first impression is that the app’s purpose is easy to understand. It focuses on a narrow, urgent task, which can be useful when you do not want to sort through investment tools, savings dashboards, or complicated banking menus. At the same time, that narrow focus is also the main reason I would not treat it as a complete financial solution. A cash advance can solve a timing problem, but it does not remove the underlying expense, and the decision deserves more care than a quick tap.
How Instant Cash Advance fits into a shared household
The most realistic use case I can imagine is a shared household where one person notices that a utility payment, transport expense, or essential purchase falls before the next paycheck. The other person may be busy, away from home, or using a different phone. In that moment, having a dedicated finance app available can make the first step more convenient than searching through a bank website or calling customer support.
However, I would keep the app tied to the individual who is actually applying. On a shared device, it is tempting to let everyone use the same screen, especially if the phone belongs to the household rather than one person. That creates an avoidable boundary problem: a loan request is a personal financial action, not the same as checking a shared grocery list. I recommend that the applicant handle the session personally and that other household members discuss the decision separately.
Best Parts of Instant Cash Advance
Things to Keep in Mind About Instant Cash Advance
This distinction matters because a fast interface can make a serious commitment feel routine. If I were using the app before a bill was due, I would first write down the exact amount needed, the date the money would be available, and the repayment obligation. Only then would I open the app. That small pause helps prevent borrowing more than the immediate need simply because the option is visible.
For couples or housemates, the useful workflow is coordination before application, not simultaneous tapping. One person can identify the shortfall, another can check the household budget, and the applicant can review the final terms on their own device or account. Instant Cash Advance may help begin that process, but it should not be treated as a shared wallet or a substitute for agreeing who is responsible.
News and Features Related to Instant Cash Advance

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What the setup means in everyday use
The app is free to install, and it is listed for everyone, which makes the first step feel accessible. That age label should not be confused with permission or suitability for borrowing. Financial responsibility is a separate question. A young person may be able to see or open a finance app while still lacking the income, legal capacity, or experience needed to make a sensible cash-advance decision.
I would therefore set a clear household rule: only the adult whose finances are involved should enter personal details, review an offer, or submit a request. Nobody else should guess a password, handle verification, or use an unattended session. This is especially important on a family tablet or a phone passed between partners, because convenience can quietly turn into account confusion.
Don't want to read the full review?
I also recommend closing the app after reviewing an application and avoiding saved access on a device that other people regularly use. I am not presenting that as a special feature of the app; it is simply sensible handling for any personal finance service. If a household shares one phone, the safest arrangement is to keep the financial conversation shared while keeping the account activity individual.
Another practical boundary is notification awareness. If the device displays financial alerts on its lock screen, other people may see information that was meant for the account holder. I would check the phone’s general notification settings before relying on the app in a shared environment. That protects privacy without pretending that a household device can provide the same separation as a personal one.
Screenshots
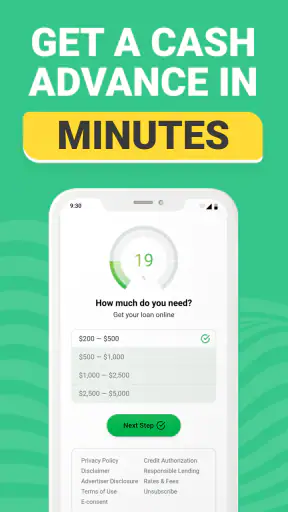
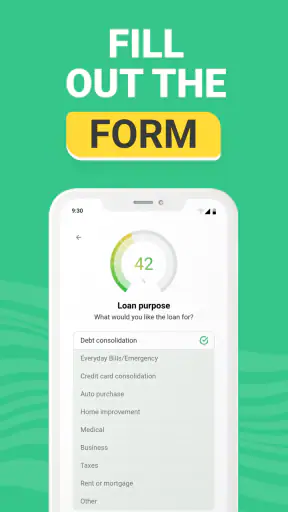
Coordinating repayment instead of only arranging the advance
The part many people overlook is what happens after the cash arrives. In a household, the person who requests the advance may not be the only person affected by the repayment. If the money covers a shared bill, the repayment still needs to be included in the next household budget. I would record it immediately in a separate note or budgeting tool, with the due date and the person responsible.
This is one area where the app’s focused design may not be enough on its own. A traditional bank app can be better for viewing balances and scheduled payments, while a spreadsheet or household budgeting app can make shared obligations clearer. Instant Cash Advance is more appropriate as a point solution for a short-term gap than as the place where two people manage their entire financial life.
A useful rule is to compare the repayment with the next reliable income, not with an optimistic estimate. If the household can repay only by taking another advance, the app is no longer solving a temporary timing issue. It is covering a recurring deficit. In that situation, I would prefer speaking with the bill provider, asking about a payment arrangement, or seeking advice from a trusted financial service before borrowing again.
There is also a coordination trap when two people use separate phones. Each person may think the other has already applied, or both may submit requests for the same expense. I would decide in advance who is responsible and confirm the amount before either person starts. That simple conversation is more valuable than any speed advantage an instant-cash tool can provide.
Trust, age, and the limits of a general audience label
The app’s everyone rating tells me that its presentation is not restricted to an adult-only entertainment category. It does not make borrowing appropriate for every user. A cash advance involves judgment about income, repayment, fees or other conditions, and personal risk. Those questions require an adult level of understanding even when the app itself is easy to access.
For parents, I would not place this app in a child’s hands as a way to learn about money. A child can learn budgeting through a simple allowance plan or a supervised savings exercise without being exposed to borrowing decisions. If the app is present on a family device, the adult should explain that opening it is not the same as being entitled to funds and that no one should enter another person’s information.
Trust also applies between adults. If a partner asks me to apply on their behalf, I would decline unless the account and financial responsibility clearly belong to me. Entering someone else’s details creates confusion about consent and repayment. The cleaner approach is for each person to use their own account and to discuss the household consequence together.
Because this is a finance product, I would read every screen carefully rather than relying on the phrase “instant cash advance.” The speed suggested by the app’s purpose should not replace checking the amount received, the total repayment, the timing, and any conditions shown during the process. If a screen is unclear, I would stop and seek clarification instead of assuming the most favorable interpretation.
My hands-on view of the app’s strengths and friction
What I like most is the directness. Instant Cash Advance does not present itself as a broad financial command center. Its store summary points toward fast funds, and that makes the intended use obvious from the start. For someone facing a short gap and wanting to investigate a cash-advance option without navigating a large banking platform, that focus can be helpful.
The app has an average rating of 4.6 from around 1.9 thousand ratings, which suggests that many people find the experience useful enough to rate positively. I treat that as a helpful signal rather than a guarantee. A good experience can depend on the applicant’s circumstances, the information requested, the available offer, and the ability to repay comfortably. A high average rating does not turn borrowing into a low-risk decision.
Its scale is also worth keeping in perspective. The app has more than 10 thousand installs, so it has reached a meaningful group of users without being something I would assume every household already knows. The developer is Janssen Herman, and the current version is 1.7.4. It runs on Android 6.0 or later, which gives it broad compatibility with older Android phones.
That older-device support can be useful in a household where one person has a newer phone and another relies on an older handset. Still, compatibility is not the same as comfort. A finance app on an aging phone may be less convenient if the device is slow, shared, or frequently offline. I would use the most private and dependable device available when handling personal financial information.
The main friction is conceptual rather than technical: the app makes an urgent financial action easy to begin, while the consequences remain yours to manage. That imbalance is common in short-term borrowing tools. The convenience is real, but it can encourage a narrow focus on receiving money instead of considering the next pay cycle.
Another limitation is that I would not use it as my main budgeting system. Someone who wants category tracking, shared goals, recurring bill planning, or a long-term view of spending should look to a dedicated budgeting app or their bank’s money tools. Someone who needs a personal loan comparison may also be better served by a transparent lender-comparison service where multiple repayment options can be reviewed side by side.
On the other hand, a conventional bank app may be slower to help with a small, immediate shortfall, especially if its borrowing tools are buried among ordinary account features. A credit card can offer flexibility, but it may encourage ongoing revolving debt. Borrowing from a trusted person may be cheaper or more forgiving, though it can strain relationships. Instant Cash Advance sits among these alternatives as a convenience-first option, so I would compare the total cost and repayment pressure rather than choosing it simply because it is quick.
Three habits that make the app safer to use
My first practical tip is to calculate the smallest amount that fixes the specific problem. If a bill needs a modest top-up, requesting extra money for unrelated spending weakens the household budget. The app’s convenience is most defensible when the amount is tightly connected to a defined need and the repayment is already visible in the plan.
Second, I would take a screenshot or written note of the final repayment information for my own records, provided doing so does not expose private details on a shared device. The point is not to create a new app feature; it is to avoid relying on memory after an urgent session. I would store the note privately and compare it with the bank balance before the due date.
Third, I would use a cooling-off check before submitting. I would ask: what happens if the next paycheck is smaller, late, or already committed? If the answer is that another loan would be necessary, I would not proceed casually. This is a more revealing test than asking whether the app can provide funds quickly.
A fourth habit is to separate household agreement from account access. Discuss the purpose, amount, and repayment together, but let the applicant review and submit the request alone. That arrangement protects both privacy and accountability, particularly when the app is installed on a shared phone.
Who should consider it, and who should skip it
I can see Instant Cash Advance helping an adult who has a temporary timing problem, understands the repayment obligation, and wants a focused way to explore an advance. It may suit someone who does not need a full budgeting suite and who is comfortable checking the financial details carefully before proceeding.
I would skip it if the household is already using one advance to repay another, if the income is unpredictable, or if the requested money is for discretionary spending that can wait. I would also choose another route when the need is recurring. A conversation with a creditor, a structured budget review, or a lower-cost borrowing option may be more appropriate than repeating short-term advances.
It is not the right tool for managing shared household finances. Couples who need joint visibility should use a budgeting method designed for shared planning and keep borrowing decisions clearly assigned to one responsible account holder. It is also not suitable for children or for anyone who is being pressured by another person to apply.
After using it, my view is measured. The free finance app is clear about the kind of problem it wants to address, and its focused approach can be convenient when a genuine short-term gap appears. Its 4.6 average and growing install base show that it has found an audience, but neither should replace personal checking of the repayment terms.
For a household, the best use is narrow and deliberate: one adult, one clearly defined expense, one private account, and a repayment plan agreed before the request. The app can speed up access to an option, but it cannot make an unaffordable advance affordable. I would recommend it only to readers who understand that distinction and have already confirmed how the money will be repaid.
Instant Cash Advance FAQ
What is Instant Cash Advance?
Instant Cash Advance is a financial service app designed to help eligible users request short-term cash advances through a mobile device. After creating an account and providing the requested personal and financial information, users may receive an offer based on the provider’s eligibility requirements. It is important to understand that approval, loan amounts, repayment dates, and availability can vary by applicant and location.
Is Instant Cash Advance a guaranteed loan or instant approval app?
No, downloading Instant Cash Advance does not guarantee approval or immediate access to money. Applications are normally reviewed using information such as identity details, income, banking activity, and other eligibility criteria. Even if the app is marketed as fast or instant, processing times may differ, and some users may be declined or offered different terms than expected.
How much does Instant Cash Advance cost?
The total cost depends on the offer presented to you and may include interest, service charges, subscription fees, origination costs, or other applicable charges. Before accepting an advance, carefully review the annual percentage rate, repayment amount, due date, and any late or insufficient-funds fees. Never proceed until you understand the complete cost and payment obligations.
What information does Instant Cash Advance require?
The app may request personal details such as your name, address, date of birth, contact information, employment or income data, and banking details. This information can be used to verify your identity, assess eligibility, and process repayments. Before submitting anything, review the app’s privacy policy, check the permissions it requests, and make sure you are using the official application from a trusted source.
When and how must an Instant Cash Advance be repaid?
Repayment terms depend on the specific advance agreement you receive. The due date, amount, payment method, and frequency should be displayed before you accept the offer. Some providers may withdraw repayment automatically from a linked bank account, so users should maintain sufficient funds and monitor their account. Missing a payment can result in additional fees, collection activity, or possible effects on credit reporting.











